In every cycle, there comes a moment when semiconductor stories feel effortless. Order books are full, AI headlines are everywhere, valuations stretch, and suddenly a cluster of semi-related companies decides it is the perfect time to go public. That moment—call it “IPO heat”—is often treated as a sign of strength. Historically, it has also been a subtle warning flag: when the semi IPO market gets too hot, future returns in the sector often cool.
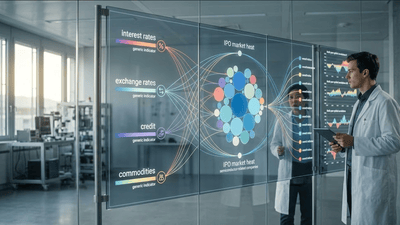
This post explores IPO heat in the semiconductor sector as a contrarian sentiment indicator, using a macro lens that includes interest rates, exchange rates, credit, and commodities. The goal is not to declare IPO waves as automatic sell signals, but to show why bursts of new listings in semis tend to cluster near sentiment peaks—and why that clustering has historically been validated as a warning that the easy part of the cycle is ending.
What Is “IPO Heat” in the Semi Sector?
IPO heat is more than a few new listings. It’s a combination of:
- Volume: A noticeable increase in the number of semiconductor and semi-adjacent IPOs within a relatively short period—foundries, memory, analog, equipment, fabless designers, and related infrastructure.
- Valuation tone: Deals pricing at rich multiples, with investors willing to pay for future growth and AI narratives rather than current earnings.
-
Strong demand, media attention, and a sense that “everyone wants in” on the semi theme.
Historically, such conditions in any sector have been associated with elevated investor sentiment. In semis, because the industry is cyclical and capital-intensive, these periods often line up with mid‑to‑late cycle peaks rather than early‑cycle value opportunities.
Why IPO Heat Reflects Macro Sentiment, Not Just Sector Stories
IPO waves don’t happen in a vacuum. They reflect broader macro conditions:
-
When policy rates are low or falling and global liquidity abundant, equity risk premia compress and investors are more willing to back new issues. Semi IPO heat tends to coincide with these risk‑on regimes. -
Stable or weak USD environments often encourage cross‑border listings and global risk‑taking. Strong FX stability makes foreign semi IPOs more attractive to global funds. -
Tight credit spreads and healthy loan growth signal strong risk appetite. Small and mid‑cap semis see an opening to go public and raise capital while conditions are favorable. -
Robust industrial and commodity trends support end demand narratives for chips, making semi stories feel safer and more compelling to IPO investors.
When you see a wave of semi IPOs, you’re not just seeing corporate opportunism; you’re seeing the reflection of a macro environment that looks benign to investors. That’s precisely why IPO heat can be contrarian: markets extrapolate that benign environment forward just as cyclical and macro forces begin to change.
Historical Patterns: IPO Clusters and Subsequent Sector Returns
Across multiple cycles, equity research has shown that IPO clustering tends to occur when sentiment and valuations are high. In semiconductors, similar patterns appear:
- During tech booms (late 1990s, mid‑2010s, AI‑driven rallies), semi‑related IPO volume increases as firms try to capitalize on investor enthusiasm.
- These periods often coincide with strong sector performance, low perceived risk, and aggressive growth forecasts.
- In the subsequent 12–36 months, sector returns frequently moderate or correct as fundamentals, competition, and macro cycles catch up.
The historical validation, then, is not “semi IPO heat always triggers crashes,” but “semi IPO heat has tended to appear near sentiment peaks, after which forward returns have been lower or more volatile than in periods when IPO activity was subdued.” For contrarian investors, hot IPO markets are signals to reassess risk rather than chase it.
Interest Rate Cycles: IPO Heat Near Policy Inflection Points
Rate cycles add another layer of context:
-
Low discount rates support higher valuations and strong IPO interest. Semi firms may see an attractive opportunity to list while financing is cheap. -
As the market begins to price in higher rates or the end of ultra‑easy policy, IPO windows can still look open but risk premia slowly rise. -
IPO heat that persists into early tightening can be particularly contrarian—markets backing long-duration semi stories just as discount rates are poised to increase.
Historically, semi IPO clusters often appear when rates are low and rising slowly, or when the market believes growth and inflation are well‑managed. Contrarians note that such beliefs can be fragile. When rates eventually move higher or liquidity tightens, the speculative edge of the IPO cohort tends to suffer most, validating IPO heat as a late‑cycle indicator.
Exchange Rates and Global Capital Flows
Global semi IPOs—listing in the US, Asia, or elsewhere—also reflect FX conditions:
-
Lower dollar strength can encourage foreign listings and international participation, boosting IPO volumes. Safe FX regimes make capital more willing to chase sector stories. -
Listing appetite can cool, but a lag often exists; some IPOs still come to market based on prior plans, even as global risk sentiment deteriorates.
From a contrarian standpoint, semi IPO heat in periods of strong global risk appetite and relatively calm FX can be a sign that investors are underpricing cross‑border and currency risks. If FX volatility returns or the dollar strengthens notably, the newly listed semi cohort may find foreign capital less sticky, contributing to post‑IPO underperformance relative to established names.
Credit and CapEx: Why Issuers Go Public When They Do
Semiconductor IPOs are often motivated by funding needs:
-
-
When credit spreads are tight, private financing is abundant; firms can choose between staying private or going public based on valuation. When spreads widen, equity windows may close, motivating late‑cycle rushes. -
In risk‑on credit environments, investors are more sympathetic to long‑term capex stories and less sensitive to near‑term cash burn.
Historically, when semi IPO volumes soar in tandem with tight credit and aggressive capex narratives, contrarians ask: How many of these projects will be funded when credit spreads eventually widen? When that shift occurs—credit conditions deteriorate after IPO heat—it tends to validate the idea that IPO waves were a sentiment peak, not a subtle bargain signal.
Commodities and Industrial Demand: The Backdrop for Semi Stories
Semi IPOs are easier to sell when industrial and consumer demand looks strong:
-
Rising metals and energy prices and robust PMIs signal a healthy environment for chips in autos, machinery, and consumer electronics. IPO stories about capturing that demand resonate. -
Tech‑driven semi demand (AI, cloud) can create strong narratives even if traditional industrial indicators are mixed.
Contrarian investors note that IPO heat often coincides with either the late stages of industrial upcycles or early exuberance about new tech themes. If commodities roll over or industrial demand softens after the IPO wave, semi names that went public on peak cycle narratives often underperform. That ex‑post behaviour validates IPO heat as a sign that demand expectations, both industrial and tech, were inflated.
Sentiment Mechanics: IPOs as Self-Reinforcing Signals
From a behavioural perspective, IPO heat is both driven by sentiment and feeds back into it:
-
The decision to go public implies management beliefs that valuations are attractive and investor appetite strong. -
Many view clusters of high‑profile semi IPOs as proof that the sector is “hot,” reinforcing momentum and broad fund positioning. -
As more semi IPOs hit screens, investors eventually become more selective, potentially leading to weaker reception for later deals.
Contrarian frameworks invert this logic: the more signals of uncritical confidence (crowded semi IPO calendar, aggressive valuations, oversubscription), the more likely it is that forward returns will be lower. Historical validation, across sectors and in semis, supports that view. Pricing and sentiment tend to peak before fundamentals do—and IPO heat is one of the clearest signs of that peak.
Historical Validation: What Happened After Prior Semi IPO Waves?
While details vary by cycle, we can outline common outcomes:
-
Semi indexes and leading names often rally for months or years before IPO volumes surge, fueled by robust earnings, liquidity, and narratives. -
A period of multiple listings, some of which are high‑quality but many of which are earlier‑stage or more speculative—memory plays, niche analog, emerging equipment suppliers. -
- Short term: continued volatility, with some IPOs popping and others fading.
This pattern validates IPO heat as a contrarian indicator: by the time many semi firms feel confident enough to go public at rich valuations, the sector’s risk/reward balance is usually less favourable than earlier in the cycle. Not all IPOs disappoint, but as a cohort, they tend to perform worse than incumbents when macro sentiment inevitably cools.
Using IPO Heat as Part of a Macro-Aware Strategy
For investors, IPO heat in the semi sector is most useful as one piece of a macro-aware toolkit:
-
Look at IPO volumes alongside rates, FX, credit spreads, and manufacturing/tech indicators. IPO heat in an environment of tightening policy or widening credit is more contrarian than IPO heat in early easing phases. -
Treat semi IPOs during hot periods as high‑beta, high‑risk exposure; focus on names with strong balance sheets, clear competitive advantages, and realistic capex plans. -
If semi IPO waves coincide with extended valuations and peak narratives, consider moderating sector overweight, emphasizing quality incumbents rather than broad beta. -
Recognize that IPO windows close faster than they open; don’t assume that abundant offerings imply sustained structural demand for all new capital in the sector.
In other words, use IPO heat not as a timing tool on its own, but as a sentiment overlay on a macro and fundamental view. When multiple indicators align—hot IPO markets, easy liquidity, stretched valuations, late‑cycle signals—it’s a stronger contrarian sign than any one data point alone.
Closing Thoughts: When New Listings Say “Watch Your Step”
“IPO Heat in the Semi Sector as a Contrarian Sentiment Indicator – Historical Validation” is really a reminder that markets tell stories through their actions as much as through their prices. When numerous semi firms rush to list during a period of rich valuations, easy money, and glowing narratives about AI and digital transformation, they are reading the same sentiment that investors see—and trying to harness it.
History suggests that these waves of enthusiasm often mark the later stages of a cycle, not the start. That doesn’t make semi IPOs bad; it makes them signals. For a contrarian, those signals say: stop, look at the macro backdrop—interest rates, exchange rates, credit, commodities—and reconsider how much risk you want in a sector that’s just told you, loudly, how confident it feels. The chips will keep advancing; the question is whether you’re paying peak‑cycle prices for that advance. IPO heat is one way the market lets you know when that risk has quietly risen.